Raleigh Mortgage Blog

  • 620 Credit Score to Buy a House in Raleigh? Real Answer

    620 credit score to buy a house in Raleigh is enough to qualify for both FHA and conventional financing, according to Logan Martini of Martini Mortgage Group. FHA opens at 580, conventional pricing typically starts at 620, and debt-to-income ratio and reserves often matter as much as the score itself. On a $350,000 Raleigh purchase, the difference between FHA and conventional cash-to-close runs about $5,250. Rate pricing tracks Freddie Mac’s national average, currently 6.67 per
  • Condo Mortgage Rules Raleigh NC: What Changed in 2026

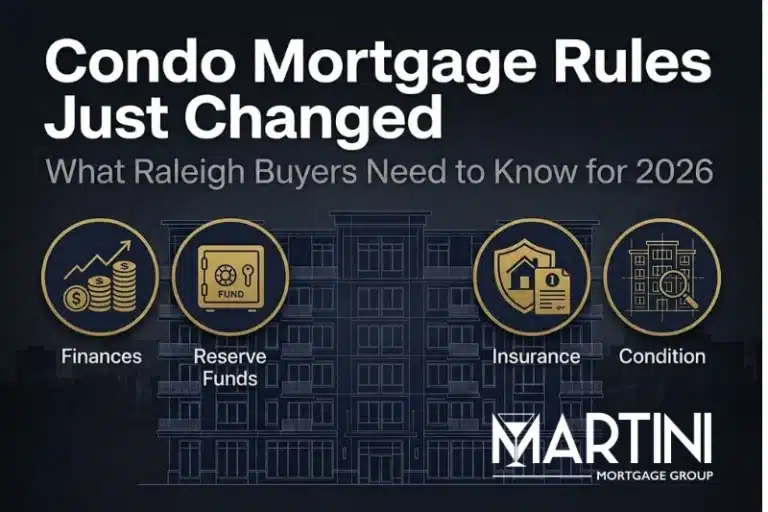
    Condo mortgage rules Raleigh NC changed in 2026 when Fannie Mae and Freddie Mac retired the fast-track review path roughly 40% of condo loans used to rely on. Kevin Martini and Logan Martini of Martini Mortgage Group have seen the shift firsthand across Raleigh, Wake County, and the Triangle, where North Carolina’s lack of a state reserve-study mandate leaves many HOAs unprepared for the new 15% reserve standard. Buildings with thin reserves or outdated reserve studies can now slow or derail a loan regardless of the buyer’s credit profile. The building’s paperwork, not just the borrower’s file, decides the timeline in 2026.

  • 10 Mortgage Terms Raleigh Homebuyers Need to Know Cold

    Mortgage terms Raleigh homebuyers need to know cold rarely get explained in plain language until a stressful moment mid-contract. Kevin Martini and Logan Martini of Martini Mortgage Group translate APR, PMI, DTI, due diligence, underwriting, and six other essential terms into the real dollar amounts and deadlines Wake County and Triangle buyers actually encounter. The guide shows why a $400,000 Raleigh loan can carry $165 to $330 a month in PMI, why North Carolina’s due diligence fee is non-refundable the moment it’s paid, and why comparing APR, not just rate, is the only way to see a loan’s true cost. Buyers who read this before writing an offer negotiate from a fundamentally stronger position.