Raleigh Mortgage Blog

  • Income Needed for a 500K House in Raleigh: The Real Number

    Income needed for a 500K house in Raleigh is not a single number pulled from a national calculator. It ranges from about $134,000 to $165,000 a year depending on down payment size, existing debt, and the mortgage rate locked at closing. Kevin Martini of Martini Mortgage Group built this breakdown using Wake County’s actual combined property tax rate and Freddie Mac’s current 30-year average, not a generic estimate. A buyer putting 20 percent down needs meaningfully less income than one putting 5 percent down, even on the identical Raleigh house. The real number is decided at the closing table, not by the price tag alone.
  • 620 Credit Score to Buy a House in Raleigh? Real Answer

    620 credit score to buy a house in Raleigh is enough to qualify for both FHA and conventional financing, according to Logan Martini of Martini Mortgage Group. FHA opens at 580, conventional pricing typically starts at 620, and debt-to-income ratio and reserves often matter as much as the score itself. On a $350,000 Raleigh purchase, the difference between FHA and conventional cash-to-close runs about $5,250. Rate pricing tracks Freddie Mac’s national average, currently 6.67 per

  • Condo Mortgage Rules Raleigh NC: What Changed in 2026

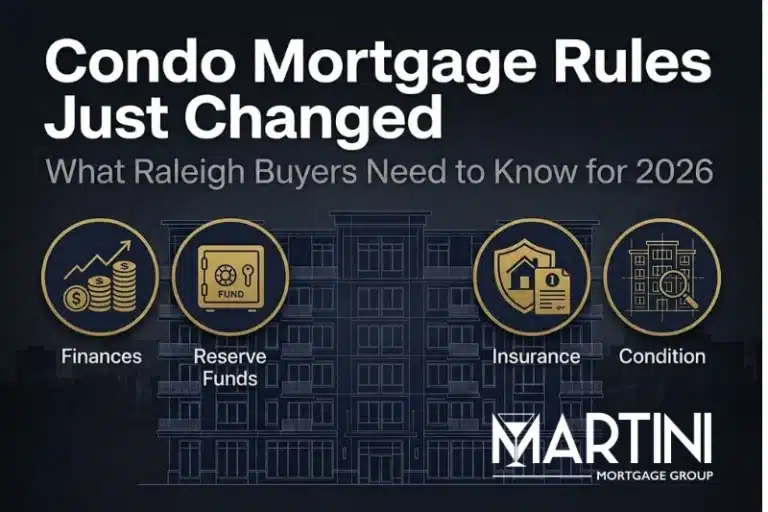
    Condo mortgage rules Raleigh NC changed in 2026 when Fannie Mae and Freddie Mac retired the fast-track review path roughly 40% of condo loans used to rely on. Kevin Martini and Logan Martini of Martini Mortgage Group have seen the shift firsthand across Raleigh, Wake County, and the Triangle, where North Carolina’s lack of a state reserve-study mandate leaves many HOAs unprepared for the new 15% reserve standard. Buildings with thin reserves or outdated reserve studies can now slow or derail a loan regardless of the buyer’s credit profile. The building’s paperwork, not just the borrower’s file, decides the timeline in 2026.